
Toyyibat Qasim
Nigeria will require an estimated $410 billion in additional investment by 2060 to achieve its net-zero emissions pathway, Vice-President Kashim Shettima has said.
Shettima said the massive financing requirement presented both a challenge and a major investment opportunity for domestic and international investors willing to participate in Nigeria’s transition to a low-carbon economy.
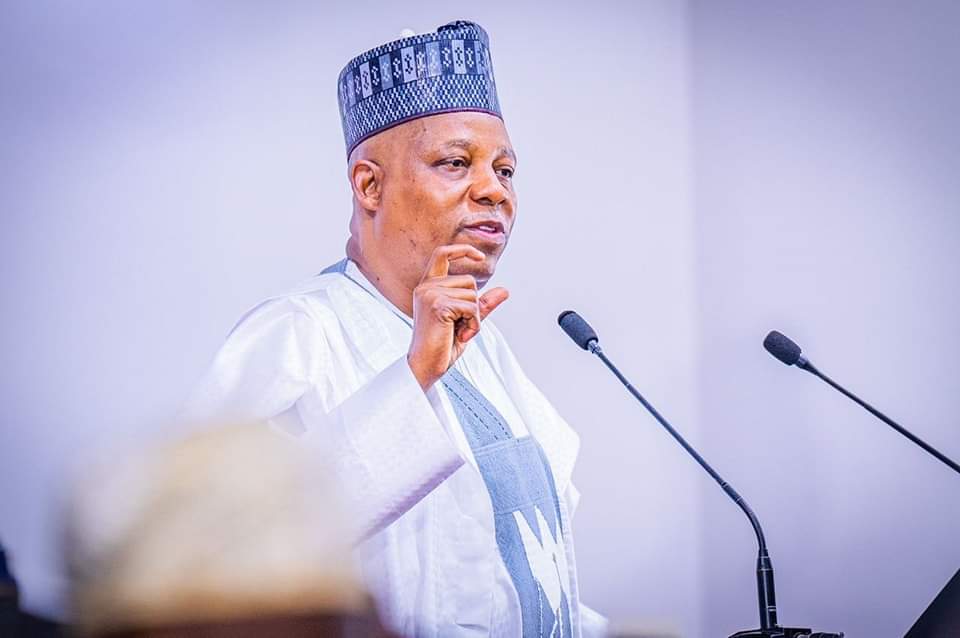
The Vice-President spoke on Tuesday at the second edition of the Decarbonising Infrastructure in Nigeria (DIN) Summit held at the United Nations House in Abuja.
He was represented at the summit, organised by his office in collaboration with the National Council on Climate Change and the United Nations Industrial Development Organisation, by his Deputy Chief of Staff, Ibrahim Hadejia.
The summit was themed, “De-risking Green Infrastructure Investment in Nigeria: Enabling Policy, Project Readiness and Risk-Sharing Solutions.”
Shettima said the government alone could not provide the enormous capital required to finance Nigeria’s long-term energy transition and infrastructure development.
He therefore called for stronger collaboration among government, private investors, development finance institutions, domestic financial institutions and institutional investors.
“Our energy transition plan estimates that Nigeria will require about $410 billion in additional investment above business-as-usual through 2060 to achieve our net-zero pathway,” he said.
“That is a significant financing requirement. But it also tells us something else: there is a very large investment opportunity ahead of us.”
The Vice-President said the central challenge was increasingly shifting from the formulation of climate policies to translating those policies into bankable projects capable of attracting financing.
According to him, investors require predictable policies, credible revenue models, adequate technical preparation and clearly defined risk-sharing arrangements before committing funds to major green infrastructure projects.
“We need the private sector. We need development finance institutions. We need domestic financial institutions and institutional investors. And, perhaps most importantly, we need projects that are properly prepared and capable of attracting that capital,” Shettima said.
He said Nigeria’s Nationally Determined Contribution 3.0 recognised the need to build a stronger pipeline of investment-ready projects, increase private-sector participation and improve access to climate finance.
The funding challenge was further highlighted by the United Nations Industrial Development Organisation’s Sub-Regional Representative in Nigeria and ECOWAS, Philbert Johnson.
Johnson said Nigeria’s physical infrastructure investment requirements were estimated at about $3 trillion by 2050, while tracked climate finance inflows remained significantly below the country’s needs.
According to him, Nigeria attracted an average of only $2.5 billion annually in tracked climate finance in 2021 and 2022, against an estimated annual requirement of $29.7 billion.
This, he said, translated into an estimated $27.2 billion annual financing gap.
Johnson identified policy and regulatory uncertainty, fragmented approval processes, unclear institutional responsibilities and inadequate revenue or offtake arrangements as major obstacles to financing green infrastructure projects.
“These projects sit at very different stages of maturity, from concepts which require feasibility work to projects ready to seek finance,” he said.
He called for the effective implementation of the Climate Change Act and stronger protection of power purchase agreements, arguing that such measures would help unlock carbon finance in Nigeria and other African countries.
Johnson said UNIDO would support project development through its Computer Model for Feasibility Analysis and Reporting (COMFAR) software and Digital Investment Promotion platform.
He said the tools were already being used by more than 11,000 practitioners across 160 countries.
The summit also highlighted the potential employment benefits of Nigeria’s transition to green infrastructure.
The Director-General of the National Council on Climate Change, Tenioye Majekodunmi, said green infrastructure projects could generate more than 300,000 jobs.
Meanwhile, the Personal Assistant to the President on Subnational Infrastructure, Musaddiq Adamu, said the DIN initiative was designed to move green infrastructure proposals beyond policy discussions and into bankable investment opportunities.
Adamu said pre-summit workshops had been held across the energy, transport, urban development and agriculture sectors to identify projects and address barriers to investment.
He recalled that the inaugural DIN Summit attracted more than 400 stakeholders and produced a green infrastructure investment pipeline and policy communiqué.
He cited the electrification of port operations as one of the outcomes of the initiative, saying engagements that followed a presentation by APM Terminals at the 2025 summit contributed to a $60 million agreement with the Nigerian Ports Authority.
According to him, the agreement is helping position Onne Port as Nigeria’s first green port.
“For me, that is an important lesson. The objective is not simply to have a good conversation. The goal is to create real investment opportunity,” Adamu said.
The summit therefore placed emphasis on turning Nigeria’s climate commitments into investment-ready projects, with participants stressing that predictable policies, stronger institutions, risk-sharing mechanisms and credible project preparation would be critical to closing the country’s huge green infrastructure financing gap.
 '
 '
Do you want to share a story with us? Do you want to advertise with us? Do you need publicity for a product, service, or event? Contact us on WhatsApp +2348183319097 Email: platformtimes@gmail.com
We are committed to impactful investigative journalism for human interest and social justice. Your donation will help us tell more stories. Kindly donate any amount HERE
 '
